
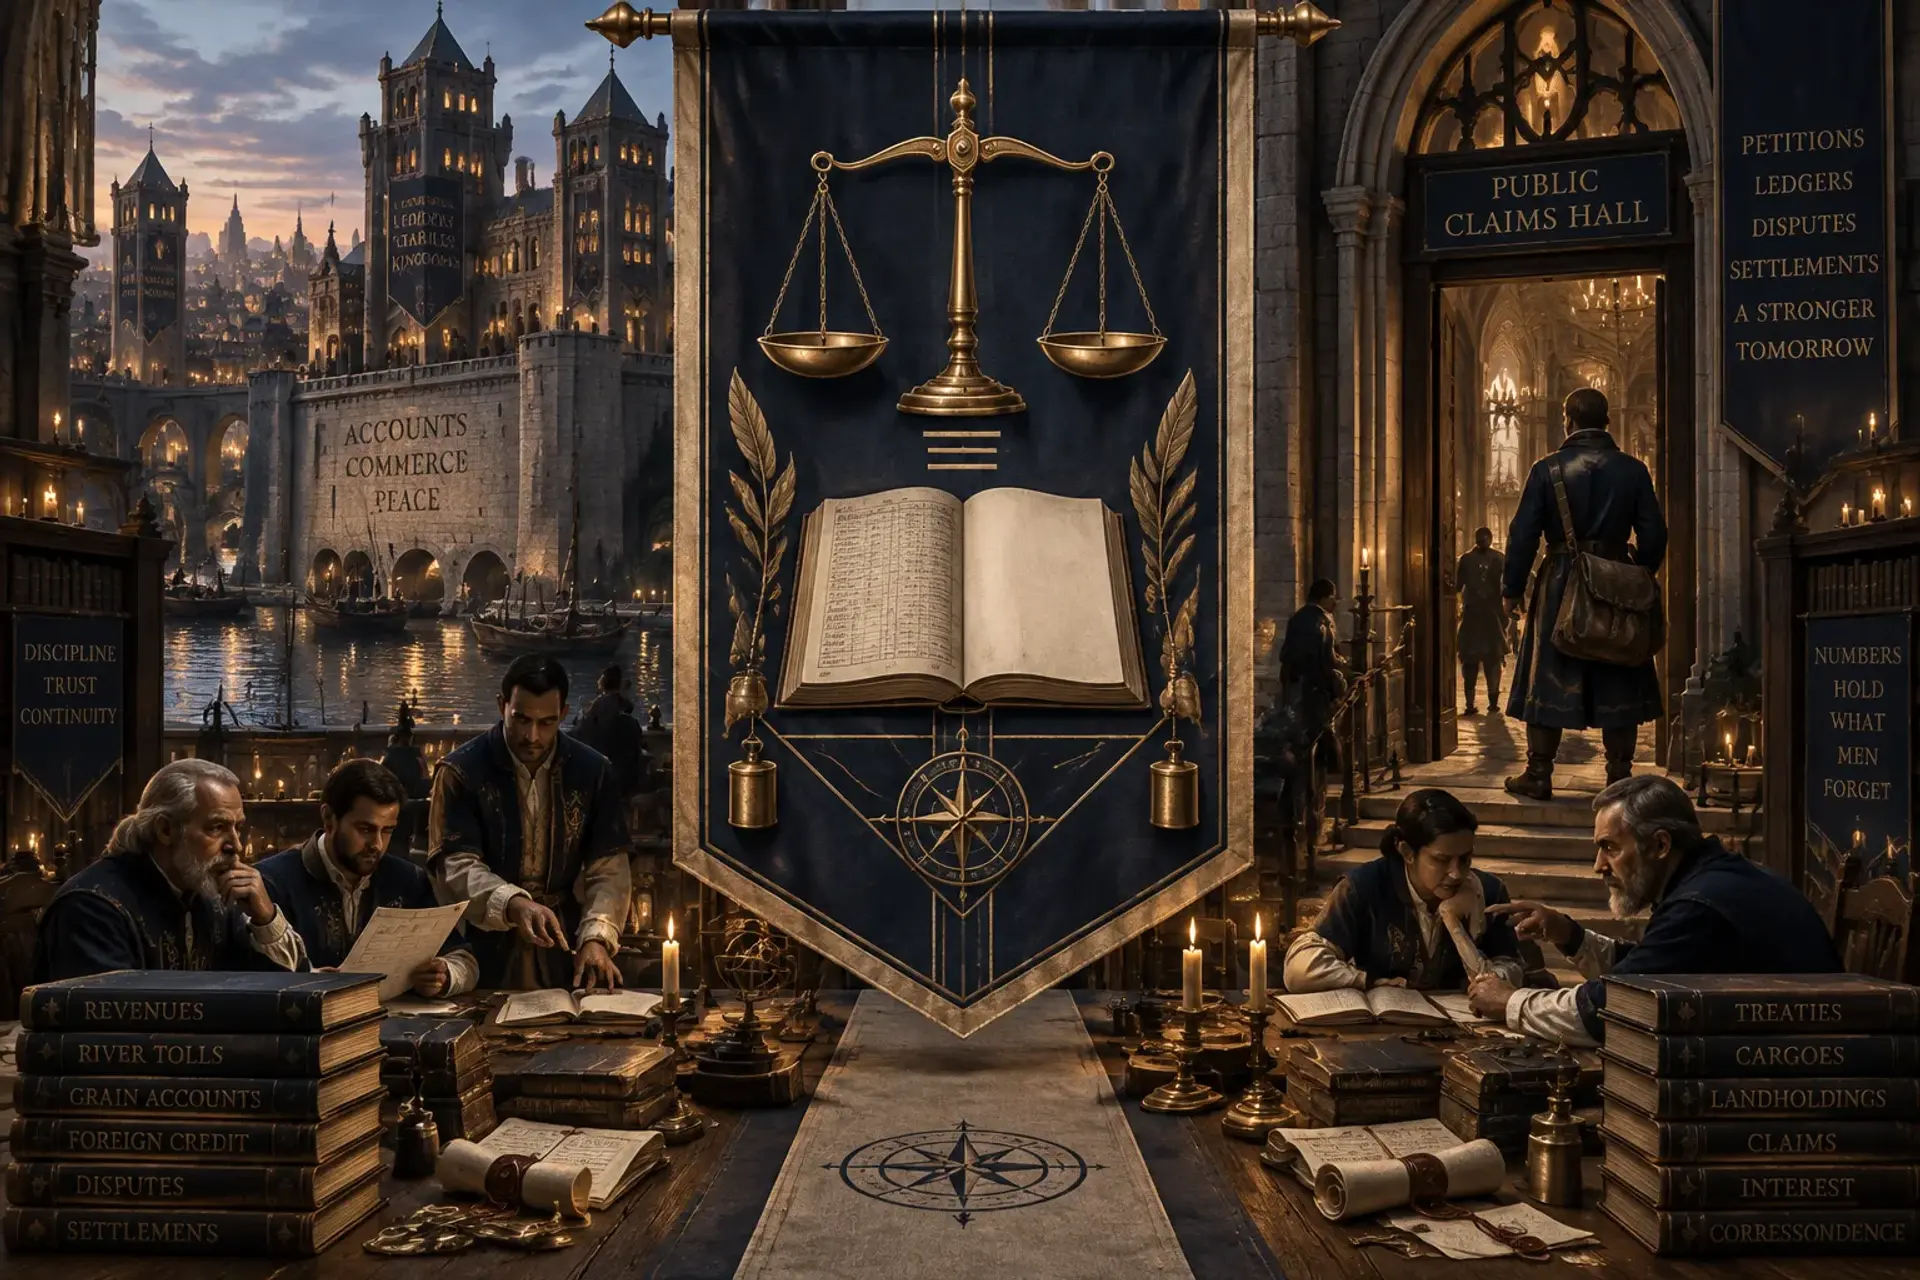
The Third Ledger Court
The first decades were marked by mistrust. Each founding house kept a private ledger in addition to the shared one, and accusations of selective copying threatened to dissolve the Court more than once. The arrangement survived because merchants found that even an unwelcome judgment was preferable to losing every claim in a trade dispute. The watershed came during the Quiet Default, when a powerful trading consortium collapsed after its principal vanished with several competing sets of records. The Court discovered that one of its own senior counters had altered the consortium’s balances to protect a favored creditor. Rather than deny the evidence, the governing seats published the conflicting entries and dismissed the counter. This public admission preserved the Court’s standing, but the compromise that followed let the founding houses keep much of the disputed collateral. To many ordinary clients, the Court had proved both its value and its limits. Over time, it expanded from record-keeping into credit clearing, secured lending, and debt recovery. Its dependence on The Notaries grew as trade stretched farther than local witnesses could travel. During a later recession, the Court offered emergency credit to small workshops, then foreclosed on many of them when the expected recovery failed. That episode created a lasting divide between members who see lending as mutual risk and those who see it as a tool for acquisition. Today, the Court is respected for keeping commerce legible, feared for what it can do with a signed debt, and increasingly divided over whether it still serves the public that made it useful.
The Third Ledger Court
- Type
- Financial institution and…
- Size
- 210 members
- Reach
- Regional
- Base
- A major trade settlement at the crossing of inland roads and a navigable river
Overview
The first decades were marked by mistrust. Each founding house kept a private ledger in addition to the shared one, and accusations of selective copying threatened to dissolve the Court more than once. The arrangement survived because merchants found that even an unwelcome judgment was preferable to losing every claim in a trade dispute. The watershed came during the Quiet Default, when a powerful trading consortium collapsed after its principal vanished with several competing sets of records. The Court discovered that one of its own senior counters had altered the consortium’s balances to protect a favored creditor. Rather than deny the evidence, the governing seats published the conflicting entries and dismissed the counter. This public admission preserved the Court’s standing, but the compromise that followed let the founding houses keep much of the disputed collateral. To many ordinary clients, the Court had proved both its value and its limits. Over time, it expanded from record-keeping into credit clearing, secured lending, and debt recovery. Its dependence on The Notaries grew as trade stretched farther than local witnesses could travel. During a later recession, the Court offered emergency credit to small workshops, then foreclosed on many of them when the expected recovery failed. That episode created a lasting divide between members who see lending as mutual risk and those who see it as a tool for acquisition. Today, the Court is respected for keeping commerce legible, feared for what it can do with a signed debt, and increasingly divided over whether it still serves the public that made it useful.
How it began
The Court began during a season of flood, failed harvests, and interrupted trade. Several rival countinghouses had each issued credit against the same cargo, while distant buyers carried contradictory invoices and no trusted way to prove which copy was genuine. Their owners met under municipal pressure and formed a shared register, agreeing to recognize one another’s seals and submit disputed accounts to a common panel. The merger was resented from the start: each house feared that a rival would gain access to its clients, reserves, and mistakes. The name Third Ledger Court refers to the independent record created alongside the two competing copies, not to a third ruling authority. Its first clerks were instructed to preserve every version and record the reason for every judgment.
How to know them
Ink blue, Dull brass, Unbleached linen
- A blank page between two written copies
- A brass weight used to hold open an account book
- Three short ink strokes beneath a certified balance
Standing
What they say they want
What they are doing now
Where it leads
A trusted network in which a debt can be verified across borders without allowing any single institution to dictate what justice means. The Court’s ideal is a common record and a local remedy. Its internal struggle is whether it can accept limits on its own power.
How others see them
Professional, cautious, and fair-minded when viewed from a distance. Merchants value its reliable records; ordinary borrowers often regard it as courteous until the moment it takes their collateral.
People
5 ranks
First Counter
Patient, exacting, and genuinely attentive to testimony. She can be compassionate in a hearing and merciless in a negotiation, believing those roles are not contradictory.
- The First Counter and two Balance Seats3 members
Set policy, approve exceptional write-offs, appoint senior officers, and decide whether the Court will support a disputed ruling. The First Counter leads, but the two Balance Seats can block major changes.
- Senior Counters12 members
Oversee credit, reserves, clients, regional branches, and sensitive negotiations. They hold most practical power because they control which questions reach the governing seats.
- Seal Clerks46 members
Maintain records, authenticate copies, investigate discrepancies, and prepare cases for arbitration. They can delay an account by flagging it for review.
- Tallyhands118 members
Handle daily bookkeeping, correspondence, estimates, and customer petitions. They are the Court’s largest group and its least protected workforce.
- Road Factors31 members
Represent the Court at distant markets, carry sealed instructions, assess collateral, and negotiate local credit. Their independence makes them useful and difficult to supervise.
Other key members
- Oa Nettle Senior Counter and likely successor
- Mino Rat Seal Clerk and keeper of an unauthorized duplicate archive
How they are organised
- Demonstrate competence with accounts, contracts, or trade records.
- Provide references from two current members or one recognized commercial client.
- Swear to preserve conflicting copies rather than silently discard an inconvenient record.
- Complete a probationary term, during which a senior member reviews all major work.
- Disclose personal debts and financial interests that could create a conflict.
Relations
5 factionsA transactional ally. The countinghouses depend on The Notaries to settle disputed invoices and authenticate long-distance credit. Their support vanishes when a ruling threatens their profits.
Operations
What they do
How they do it
Services for hire
- Record comparisonA modest fee, with higher charges for urgent or distant searchesCompare available copies of an invoice, account, or payment record and certify whether they agree.
- Credit guaranteeNegotiated interest or a fee based on the amount guaranteedArrange credit or guarantee a payment between distant parties, subject to collateral and risk review.
- Dispute preparationA retainer and a share of recovered valueOrganize records and correspondence for a disputed invoice before referral to The Notaries.
- Repayment arrangementA negotiated schedule, sometimes secured against property or future earningsRestructure a debt when the Court believes repayment is more valuable than immediate foreclosure.
What they can do
What they have
Where they are weak
Territory
Headquarters
A major trade settlement at the crossing of inland roads and a navigable riverA severe complex of counting rooms, archive vaults, interview chambers, and a public claims hall. Its most important room is the copy chamber, where three clerks independently record major transactions. The archive is dry, guarded, and carefully indexed, but not every record is equally accessible. Wealthy clients can request searches that ordinary claimants must wait months to receive.
Lands they hold
Outposts
- Coastal counting roomA coastal market districtVerify cargo accounts and arrange credit for merchants whose goods travel by sea.
- Road factor stationA caravan junction beyond the main trade routeAssess collateral, relay sealed instructions, and record transactions too distant for headquarters to witness.
- Claims officeA dense workshop quarterHear payment petitions and negotiate repayment before a disputed account reaches formal arbitration.
Secrets
Plot hooks
5 hooks- 1The Paid AccountLow to moderateReward: Personal exoneration, a modest payment, or a useful clerical contactA character receives a demand for a debt their family insists was paid. The Court’s copy says otherwise, but a junior clerk offers to show a missing receipt if the character can get them safely out of the archive district.
- 2Three Copies, Two StoriesModerateReward: Local allies, access to the claims hall, or a negotiated settlementA workshop is days from foreclosure after the Court refuses to recognize its repayment records. The party must determine whether the discrepancy is clerical error, deliberate manipulation, or an attempt by a rival client to acquire the workshop cheaply.
- 3The Price of a RulingModerate to highReward: Payment, political leverage, or a lasting relationship with either institutionThe Notaries issue a ruling that would cost the Court a fortune. Shiori asks the party to find evidence relevant to the dispute, while Oa offers a better reward for evidence that could undermine it. Both may be telling the truth about the stakes.
- 4The Uncounted PagesHighReward: Evidence capable of changing the Court, a dangerous patron, or claims to disputed assetsMino Rat has uncovered a duplicate archive tied to the Quiet Default. He asks the party to help decide whether to publish it, bargain with Shiori, or use it to protect the people whose property was seized. Several senior counters have learned that the archive exists.
- 5A Balance DueCampaign scaleReward: Regional influence, a major political debt, or the prevention of a financial takeoverA regional authority is failing, and the Court has secretly acquired claims that could make it the effective owner of roads, tolls, and public stores. The party can expose the plan, negotiate limits, or help stabilize the authority before the debt becomes enforceable.
Work they offer
What gets in the way
Rumours
Media
0 imagesNo images yet.
Turn The Third Ledger Court into a sheet
A high-res, share-ready sheet you can post or print.